
-
- monday: 8:00AM – 5:00PM
- tuesday: 8:00AM – 5:00PM
- wednesday: 8:00AM – 5:00PM
- thursday: 8:00AM – 5:00PM
- friday: 8:00AM – 5:00PM
Your Local CrossCountry Mortgage Loan Officer
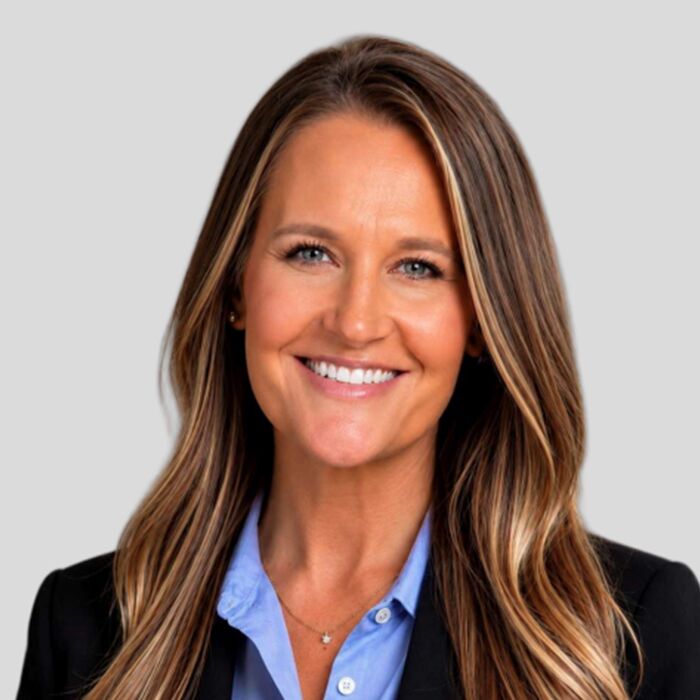
Katie Ingram

- Branch Manager/Sr. Loan Officer
- Huntsville, AL Mortgage Loan Officer
- NMLS # 882845
I’ll be with you every step of the way
Hello! My name is Katie Ingram, and I’m a branch manager and senior loan officer at the Jonesboro, AR, branch. With personal service and the support of America’s #1 Retail Mortgage Lender, I’ll help you find the right mortgage solution.
I joined the mortgage industry 15 years ago. Since then, I have learned how important communication is throughout the mortgage process. I’m big on keeping all parties informed and always being readily available to you. From pre-approval to closing and long after, I’ll be here to answer your questions and make sure your home loan continues to work for you.
When it comes to finding the right home financing, I always start by listening. We’ll talk through your goals and explore the loan options that support them. I offer a wide range of choices, including debt service coverage ratio, FHA, conventional, VA, USDA and non-QM. Together, we’ll build a plan that fits you!


Katie’s Reviews
My Videos
Guides and resources


My social posts
How much will your mortgage payment be?
Enter the basic loan terms (and additional information if you wish) to calculate your monthly mortgage payment and see a breakdown by category.
This calculator is being provided for educational purposes only. The results are estimates based on information you provided and may not reflect CrossCountry Mortgage, LLC product terms. The information cannot be used by CrossCountry Mortgage, LLC to determine a customer’s eligibility for a specific product or service.

Inspiration for your home loan journey


Frequently asked questions
-
Non-QM loans use expanded home financing criteria to give borrowers income and credit flexibility. From qualifying with bank statements or 1099 income to purchasing investment properties, Non-QM loans open doors to homeownership many don’t realize are available.
-
Also known as Investor Cash Flow loans, DSCR loans are designed to help real estate investors secure financing with their rental property’s cash flow. Instead of relying on personal income, DSCR loans use the debt service coverage ratio (DSCR) to qualify.
DSCR is calculated by dividing the monthly rental income by principle, interest, property taxes, homeowners insurance and association dues.
-
Since Non-QM loans don’t follow traditional guidelines, they’re considered riskier. That’s why lenders often require a higher down payment, interest rate and other terms.
But Non-QM loans are a safe financing option that benefits many homebuyers. Talk to a CCM loan officer to learn what’s right for you.
-
Bank Statement loans allow you to qualify for a mortgage using your bank statements instead of tax returns. These loans are designed for borrowers who have strong credit and finances but don’t have traditional income, like self-employed workers.
To qualify, you’ll use the average of your deposits over a 12- or 24-month period. If your work doesn’t provide a W-2, this may be the loan for you.
-
ITIN loans give you a way to qualify for home financing without a Social Security number. Instead, your Individual Tax Identification Number (ITIN) makes homeownership possible.
At CrossCountry Mortgage, we provide numerous ways to qualify using an ITIN. Bank statements, liquid assets, 1099 income and more can all be used to buy a home with our ITIN loan.
-
No. Conventional loans follow criteria established by the Consumer Financial Protection Bureau (CFPB). Non-QM loans use different standards that provide flexibility for borrowers who may not meet conventional requirements due to the type of home being purchased, financial circumstances or non-traditional income or employment.