

Step-by-step process to getting the keys to your new home.
-
- monday: 8:00AM – 5:00PM
- tuesday: 8:00AM – 5:00PM
- wednesday: 8:00AM – 5:00PM
- thursday: 8:00AM – 5:00PM
- friday: 8:00AM – 5:00PM
Your Local CrossCountry Mortgage Loan Officer
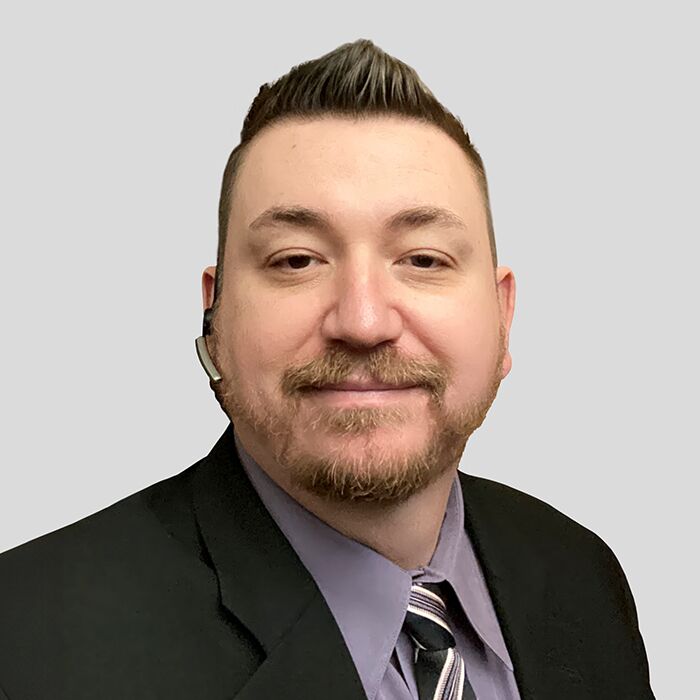
Ernest Burt
- VP of Mortgage Lending
- Denville, NJ Mortgage Loan Officer
- NMLS # 141948
I’ll be with you every step of the way
I’m Ernest Burt, Vice President of Mortgage Lending, serving homebuyers and homeowners throughout Monmouth, Ocean and Middlesex counties in New Jersey. Since 2003, I’ve had the privilege of helping clients achieve their homeownership dreams. I take pride in my accessibility, industry expertise and knowledge of a wide range of mortgage products, ensuring every client receives the guidance and support they deserve.
I specialize in all residential loans including conventional, FHA, VA, non-QM and jumbo loans. Whether this is your first home, your next home or a refinance, I’m here to make home financing feel simple. I’ll walk you through each step of the mortgage process, answer your questions and keep you updated on your loan. From start to finish, you’ll feel confident closing with America’s #1 Retail Mortgage Lender.
When I’m not working, I enjoy spending time with my family, golfing, going to the beach and volunteering in my community.


Ernest’s Reviews
My Videos
Our Team
Guides and resources


My social posts
How much will your mortgage payment be?
Enter the basic loan terms (and additional information if you wish) to calculate your monthly mortgage payment and see a breakdown by category.
This calculator is being provided for educational purposes only. The results are estimates based on information you provided and may not reflect CrossCountry Mortgage, LLC product terms. The information cannot be used by CrossCountry Mortgage, LLC to determine a customer’s eligibility for a specific product or service.

Inspiration for your home loan journey
Frequently asked questions
-
Refinancing costs typically range from 2% to 6% of the loan amount and include fees such as appraisal, title insurance, and closing costs. Factors like your loan type, location, and credit score can significantly impact these expenses. Our team can help to provide strategies that can help minimize costs.
-
To determine how much home you can afford, you’ll want to assess your financial situation. This includes your income, expenses, and debt-to-income ratio, to ensure your mortgage fits comfortably within your budget. A general guideline is to spend no more than 28% of your gross monthly income on housing costs and 36% on total debt.
-
A good credit score typically starts at 620 for conventional loans, while FHA and VA loans may accept scores as low as 500, though higher scores offer better terms. A strong credit score can help you secure lower interest rates, saving you significant money over the life of a home loan.
-
A Home Equity Line of Credit (HELOC) is a revolving line of credit that allows homeowners to borrow against the equity in their home. HELOCs function like a credit card, giving access to funds up to a set limit, which can be used for expenses like renovations or debt consolidation. You only pay interest on the amount you borrow, and the repayment terms typically include a draw period followed by a repayment period.
-
To calculate your mortgage payments, start with your loan amount, interest rate, and loan term. Your payment will depend on the interest charged over time and the repayment schedule. You can use a monthly mortgage payment calculator or connect with us to learn more.